

Ava Finance
Ava Finance, Inc.
- 4.7
- 1.69K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
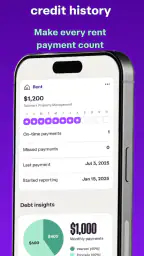
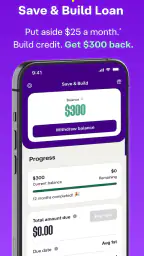
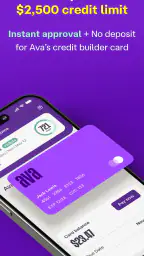
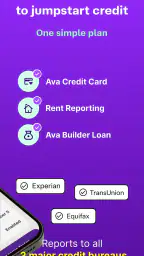
Ava Finance Pros and Cons
Pros
- Simple interface makes tracking loans and repayments easy.
- Supports multiple financial products in one app.
- Useful notifications can help prevent missed payment dates.
- Provides quick access to account and transaction information.
- Available on mobile for convenient financial management on the go.
Cons
- Eligibility and available features may vary by location.
- Interest rates and fees can differ based on personal circumstances.
- Requires sharing sensitive financial and identity information.
- Some services may depend on third-party lenders or providers.
- Customer support response times may vary during busy periods.
 Analysis by All-app
I approached Ava Finance as a practical credit-building app rather than as a complete replacement for a bank. That distinction matters. Its focus is personal finance, and the main appeal is helping someone work toward stronger credit habits through a phone-based experience. I found it most interesting for people who want a more structured way to pay attention to credit, especially when a household is trying to coordinate money without blending everyone’s accounts together.
The app is free to download, aimed at an Everyone audience, and developed by Ava Finance, Inc. Its public reception is encouraging, with a 4.7 average from around 17 thousand ratings and more than 500 thousand installs. Those figures suggest that it has reached a meaningful audience, but they should not be confused with a promise that every person will see the same credit outcome. Credit products are personal, and the useful question is whether Ava fits your financial routine, not simply whether it is popular.
How Ava Finance fits into a shared household
A realistic use case is a household where one person manages most of the bills while another adult is trying to become more deliberate about credit. The person handling rent, utilities, groceries, and subscriptions may already use a bank app for transactions. The other person may not need another general-purpose banking dashboard; they may need a focused place to understand and follow a credit-building routine.
That is where Ava can make sense. I would treat it as an individual tool inside a shared financial plan, not as a household wallet. Each adult should keep a clear boundary around their own account, login, identity, and financial decisions. A partner can help someone remember a payment date or review a monthly plan, but that does not turn the app into a shared account-management system.
This distinction is easy to overlook when a couple uses one tablet or a family shares a phone. Finance apps are not like shared shopping lists. Leaving an account open on a common device can expose sensitive information, and handing a login to another person makes it harder to know who is responsible for an action. I recommend using Ava only under the account holder’s own profile and keeping the device protected with its normal screen lock.
For a household with separate finances, Ava can support coordination without forcing financial merging. One person might use it to stay consistent with a credit goal while the other continues using a conventional bank, card issuer, or budgeting app. That arrangement is cleaner than trying to make one app represent everyone’s income, debts, and spending.
What the first setup should accomplish
The first session is best treated as a boundary-setting exercise. Before entering anything, decide whose credit journey the app is supporting. If two adults both want to use it, they should establish their own accounts rather than taking turns inside one profile. This avoids mixing personal information and makes later conversations about progress much less confusing.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I also suggest deciding what Ava is supposed to do in your routine. Is it a reminder to stay engaged with credit? A place to follow a credit-building product? A supplement to an existing budget? The answer affects how often you open it and what you compare it with. If you already use a bank app for balances and a spreadsheet for household planning, Ava does not need to replace either one.
Another sensible boundary is to separate credit-building activity from everyday spending decisions. A person can use Ava for its intended financial purpose while continuing to monitor cash flow elsewhere. That separation helps prevent a common mistake: assuming that progress in one credit-focused tool means the household can safely take on a new recurring payment or spend more than usual.
The app runs on Android with a minimum operating-system requirement of 9, so compatibility is worth checking before planning around it. I would also keep the app updated; the current version is 5.1.5831. An update number is not a measure of financial quality, but using the current release can reduce avoidable friction when the app changes its screens or account flow.
Coordinating without sharing control
For couples or relatives, the most useful coordination is usually simple and deliberate. The account holder can explain the purpose of Ava, the payment or review routine they are following, and which household dates matter. The helper does not need access to the account to provide a reminder. This keeps responsibility with the person whose credit is involved.
A shared calendar can handle the household side of the process. For example, if one person is paid near the end of the month and the household reviews recurring bills shortly afterward, they can agree on a short check-in. The Ava user can open the app privately, confirm what needs attention, and then discuss only the household-level impact. This is more respectful than passing a phone around or asking for login details.
I would be especially careful when one adult is helping another adult who is new to credit. Assistance should mean explaining terms and checking that the person understands the routine, not making decisions on their behalf. Credit-building is tied to an individual’s financial history, so a well-meaning partner who taps through screens or agrees to something without clear permission can create confusion at exactly the moment the user needs confidence.
For parents and older teenagers, the situation is more sensitive. The Everyone content rating describes the app’s general audience classification, but it does not automatically answer whether a particular financial product is suitable for a minor or whether a parent should supervise its use. I would discuss eligibility, responsibility, and the consequences of missed obligations before involving a young person. The app should not be treated as a shortcut around adult guidance.
Trust, privacy, and account ownership
Trust in a finance app is not only about whether the interface feels polished. It is also about knowing who controls the account and how decisions are made. Ava Finance, Inc. is the developer behind the app, while the person using it remains responsible for understanding the terms of any financial service connected to their account. I would read each in-app explanation carefully instead of accepting a prompt simply because it appears during setup.
Household trust works best when everyone knows the difference between visibility and control. A partner may know that the other person is working on credit, but that does not mean they should see every screen. Similarly, a person who is helping with bills should not assume they are entitled to another adult’s financial details. Keeping these lines clear can prevent arguments later, particularly when household money is already tight.
Shared devices deserve extra attention. I would avoid storing the app on a tablet that guests regularly use, and I would not leave it open while someone else is browsing. If a household must use one device, the account holder should finish the session, close the app, and lock the device. Those are ordinary precautions, but they matter more for finance than for entertainment apps.
I also recommend preserving a second way to understand the household budget. Ava may be useful for the credit-focused part of the picture, but it should not become the only record of rent, utilities, debt payments, or available cash. A basic budget note or bank statement review gives the household a wider view and makes it easier to spot a problem that a credit-building app is not designed to explain.
Where it is stronger than familiar alternatives
The clearest alternative is doing nothing beyond using a regular bank account. That approach may feel simpler, but it can leave credit-building goals vague. Ava gives the user a dedicated place to pay attention to that goal instead of hoping ordinary spending will somehow produce the desired result.
Another alternative is a general budgeting app. Budgeting tools are usually better for categories, cash flow, and household spending plans. Ava is more narrowly relevant to someone whose immediate concern is credit development. I would use a budgeting app when the main problem is overspending or bill organization, and consider Ava when the main problem is building a consistent credit routine.
Credit-monitoring services are a different comparison again. They can be useful for watching reports or changes, but monitoring is not the same as building habits. Ava’s appeal is the possibility of turning attention toward action rather than only displaying a score or alert. Still, someone who mainly wants report surveillance may find a monitoring-focused service more direct.
A bank or card issuer may remain the better choice for everyday account management. Those services are usually where I would look for transaction history, deposit activity, and the full context of a financial relationship. Ava should be judged as a focused companion, not as a universal replacement for those tools.
Practical routines that make the app more useful
My preferred routine would be short and consistent. I would choose one regular day to review Ava, then compare that review with the household’s bank balance and upcoming obligations. The purpose is not to stare at the app every day; it is to connect the credit goal with real cash flow. If the household cannot comfortably cover its normal commitments, credit progress should not encourage extra spending.
A second useful habit is to write down the reason for using the app in plain language. “I want to establish a more consistent credit routine” is clearer than “I want a better score quickly.” The first statement supports steady behavior, while the second can tempt someone to chase a result they cannot control on a precise schedule.
A third tip is to review any recurring commitment as part of the household budget before accepting it. A payment that looks manageable in isolation can become stressful alongside rent, transport, groceries, and existing debt. This is particularly important when two people coordinate money but only one person owns the Ava account. The household should discuss affordability, while the account holder makes the final decision for their own profile.
I would also keep expectations realistic when checking progress. Credit outcomes can depend on several parts of a person’s financial history, and no app should be treated as a guaranteed fast track. The store summary presents Ava as a way to build credit fast, but I would interpret that as the app’s central purpose rather than a personal promise. Consistency and affordability matter more than rushing.
Friction points and people who should skip it
The biggest limitation is scope. Ava is not the right single tool for someone who wants detailed household budgeting, investment tracking, bill negotiation, or a complete view of every financial account. Adding it to an already crowded collection of finance apps may create more maintenance instead of clarity.
It may also be a poor fit for someone who is looking for instant results. Credit-building is not a useful area for impulsive experimentation. If a person is already struggling to cover essentials, the priority should be stabilizing cash flow and seeking appropriate financial guidance, not adding another obligation simply because it is presented through a convenient mobile interface.
People who are uncomfortable managing a separate finance account may prefer to work directly with their bank or a trusted credit counselor. Ava’s phone-first format is convenient, but convenience does not remove the need to read terms, understand responsibility, and keep track of the wider budget.
Households should also skip the idea of using one shared Ava login for everyone. That arrangement may appear efficient, yet it blurs ownership and makes private financial information unnecessarily visible. Separate personal use, combined with simple household reminders, is the safer and more understandable approach.
My household verdict
After looking at Ava through the lens of everyday shared finances, I see it as a focused credit-building companion for an individual, not a family finance hub. It can fit well when one adult wants a clearer routine and the household is willing to support that goal without taking control of the account. The free price lowers the barrier to trying it, but it does not remove the need to evaluate every connected financial commitment carefully.
The app is most convincing for someone who already has basic control of their spending and wants to give credit-building more attention. It is less convincing for a person who first needs a complete budget, debt plan, or direct help with financial hardship. In those cases, a bank’s tools, a dedicated budgeting system, or qualified advice may be more useful as the starting point.
Its 4.7 average and broad installation base make it worth considering, while the Everyone rating makes it approachable from a general-audience perspective. Even so, I would make the decision based on account ownership, affordability, and the role Ava will play beside the tools the household already uses. I would not install it on behalf of someone else or promise that it will deliver a particular credit result.
My recommendation is straightforward: try Ava if you want an individual, mobile-centered way to stay engaged with credit and can maintain clear boundaries around household access. Keep your bank and budget records in the picture, discuss shared financial effects openly, and let the account holder remain in control. Used that way, Ava Finance has a sensible place in a household’s routine without pretending to solve every money problem.
Frequently Asked Questions
What is Ava Finance and what can I do with it?
Ava Finance is a digital finance application designed to help users manage money-related activities from a mobile device. Depending on the services available in your region, it may provide tools for viewing balances, tracking transactions, organizing financial information, or accessing related financial products. Before downloading, check the official description carefully because features, supported currencies, eligibility rules, and available services can differ by country and account type.
Is Ava Finance safe to use for managing financial information?
Ava Finance may use account protection measures such as login credentials, device verification, encryption, and security notifications, but no financial application is completely risk-free. During our review, users should pay close attention to the permissions requested and download only from an official app store or verified source. Never share passwords, one-time codes, recovery phrases, or banking details with anyone claiming to represent the service.
Does Ava Finance require identity verification or personal information?
Financial applications commonly request personal details to create an account, verify identity, comply with anti-fraud regulations, and provide access to certain services. Ava Finance may ask for information such as your name, email address, phone number, date of birth, or identity documents, depending on the features you use. Review its privacy policy and terms before registering, especially if you are concerned about data storage or third-party sharing.
Are there fees, limits, or eligibility requirements in Ava Finance?
Users should review the fee schedule before using Ava Finance because costs can depend on the specific feature, transaction type, payment method, currency, or location. There may also be account limits, verification requirements, minimum ages, geographic restrictions, or waiting periods. Some services may appear available in the app but remain inaccessible until your account is approved or additional information has been submitted.
What should I do if Ava Finance does not work or I have a transaction problem?
If Ava Finance fails to load, displays incorrect information, or a transaction appears delayed, first check your internet connection and update the application through the official store. Avoid repeating a payment until you confirm whether the first attempt succeeded. Save screenshots and transaction references, then contact support through the in-app help section or official website. Do not rely on unofficial social-media accounts for financial assistance.


